Buyer guide with Colleen Olivas
CalHFA Explained: 7 Things to Know Before You Apply (2026, San Bernardino County)
By Colleen Olivas, NMLS #379721, The Brandon Drew Group, a division of New American Funding. Colleen started in escrow and worked her way through every role in mortgages, up to underwriter. She is a CalHFA Preferred Loan Officer. Last reviewed November 2026
Quick answer
CalHFA, the California Housing Finance Agency, offers first-time buyer programs through approved lenders. In San Bernardino County, its 2026 income limit is $210,000 for its first mortgage and second loan programs (Dream For All has its own lower limit). Its main help with the cash to buy, MyHome Assistance, is a loan you repay later, not a gift. Dream For All closed to new applications on March 16, 2026, but CalHFA says buyers who weren't selected can still look at MyHome or CalPLUS with ZIP. Programs are subject to eligibility and availability.

On this page (9 sections)
Why this matters here
San Bernardino County's housing department says on its website that it no longer offers down payment assistance, and points residents to CalHFA and outside agencies (checked October 28, 2026). The City of Rancho Cucamonga's housing page lists no down payment program either. CalHFA and GSFA are two good places to start.
You don't apply to CalHFA directly
You apply with a lender, not with CalHFA. CalHFA's programs are only available through a CalHFA-approved lender. CalHFA also says a lender's branch "may or may not" have a loan officer trained in its programs, so it's worth asking any lender: do you personally do CalHFA loans?
You can search CalHFA's own list of approved lenders and loan officers on its website.
"First-time buyer" doesn't mean "never owned"
For CalHFA MyHome, a first-time buyer is someone who hasn't owned a principal residence in the past three years. That includes a home your spouse owned that you lived in. If you owned a home longer ago than that, you may still count.
Try this: write down the last date you owned, or lived in, a home that you or your spouse owned. That's where the answer starts.
The income limit is probably higher than you think
CalHFA's income limit for San Bernardino County is $210,000 for its first mortgage and second loan programs except Dream For All, effective June 30, 2026. Dream For All's limit for the county is $168,000. There is no sales price limit for CalHFA programs, though loan limits still apply.
Look up the limit before you rule yourself out, and ask your lender exactly which income they count. CalHFA's Lender Program Manual says: "The income of all borrowers cannot exceed the published CalHFA Income Limits established for the county in which the property is located." If one spouse isn't buying, the manual says: "The non-purchasing spouse may not be on title, have any vested interest in the property, be on the purchase agreement, or be added to title after loan closing" (CalHFA Lender Program Manual, revised August 2026, checked November 8, 2026). Lenders, including ours, can add stricter rules.
MyHome is a loan, not a gift
CalHFA MyHome Assistance is a second loan that helps with the down payment and closing costs. It pairs with a CalHFA first mortgage. Repayment waits while you keep that first loan. It comes due when you sell, transfer the title, pay off or refinance the first loan, or if a Notice of Default is recorded and not rescinded.
That can be a fair trade. Just know you'll repay it, and ask for a one-page summary of what you'll owe, when, and to whom.
Refinancing later means paying off the second loan
CalHFA requires its second loans to be paid in full if you refinance the first mortgage. If you think you may refinance someday, tell your loan officer at the start so you can plan for it.
Everyone on the loan has to live in the home
With MyHome, every borrower, including any co-borrower, must be a first-time buyer and move in within 60 days of closing. A co-signer who won't live in the home isn't allowed. At least one first-time borrower also completes a homebuyer education course, online or through a HUD-approved counseling agency.
Decide early who will be on the loan. It changes which programs fit.
Dream For All closed, but it wasn't the only option
Dream For All is a shared appreciation loan: you repay what you received plus a share of the home's increase in value when you sell or pay off the first loan. Buyers were chosen by random drawing, and the 2026 application portal closed on March 16, 2026.
If you weren't selected, CalHFA says you can still work with a CalHFA-approved lender and look at:
- MyHome Assistance, for down payment and closing costs (see above).
- CalPLUS with ZIP, a CalHFA first mortgage paired with ZIP, a program that helps with closing costs. → CalPLUS with ZIP
- Outside CalHFA, GSFA Platinum from the Golden State Finance Authority, a California public agency. It offers down payment and closing cost help and doesn't require being a first-time buyer. → GSFA Platinum
Each has its own rules and trade-offs. For the CalHFA programs, credit and debt limits follow the first mortgage you choose. GSFA Platinum's standard option is a second loan with monthly payments. Every program has eligibility rules, and funds are limited. Compare the whole loan, not only the help.
→ More: Dream For All closed: what now?
What we do differently
When you call our office, you'll be greeted by a warm staff, willing and able to help you get started, and we'll set up an appointment for you and Colleen to talk about your goals and dreams. Colleen worked her way up to underwriter, so she reads these program guidelines closely.
We can't tell you whether a program fits before we see your numbers. We can tell you which questions to ask, and give you a straight answer, even if it's "not yet."
Call our office: 909.944.8800.
Your next step
Talk it through with Colleen
A short call helps you know what to ask and what to have ready. No pressure.
 Free guide · PDF · California editionThe Homebuyer's Guide
Pre-approval, CalHFA, GSFA and the other down payment programs, in plain words. Read it at your own pace.
Download the free guide
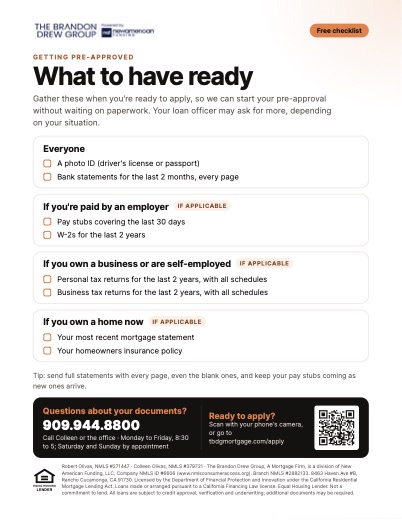 Free checklist · PDF · one pageWhat to have ready
The documents to gather when you're ready to apply, so we can start your pre-approval without waiting on paperwork.
Download the checklist
Questions buyers ask
Can I apply to CalHFA directly?
No. CalHFA programs are only available through a CalHFA-approved lender. You apply with the lender, and the lender reserves the CalHFA loan after you have a signed purchase contract.
What is the CalHFA income limit in San Bernardino County for 2026?
$210,000 for CalHFA first mortgage and second loan programs except Dream For All, effective June 30, 2026. Dream For All's limit is $168,000. Limits can change, so check CalHFA's income limit page on the day you apply.
Is CalHFA MyHome Assistance a grant?
No. It's a deferred second loan. Repayment waits while you keep the first mortgage. It's repaid when you sell, transfer title, refinance or pay off the first loan, or if a Notice of Default is recorded and not rescinded.
Can my parents co-sign a CalHFA MyHome loan?
Not if they won't live in the home. MyHome doesn't allow non-occupant co-borrowers or co-signers.
Is Dream For All open in 2026?
No. The 2026 application portal closed on March 16, 2026, and CalHFA hasn't announced a new application round (checked November 2, 2026).
Does San Bernardino County have its own down payment assistance?
The county's housing department says it no longer offers down payment assistance and points residents to CalHFA and other agencies (checked October 28, 2026).
Sources10 sources · show all
- CalHFA MyHome Assistance program guide, last revised Oct 19, 2026: https://www.calhfa.ca.gov/homeownership/programs/myhome.pdf
- CalHFA income limits, effective 06/30/2026: https://cloud.calhfa.ca.gov/homeownership/limits/income/income.pdf
- CalHFA Lender Program Manual, last revised August 2026 (income of all borrowers; non-purchasing spouse), checked November 8, 2026: https://www.calhfa.ca.gov/homeownership/programs/lender-manual.pdf
- Dream For All income limits, effective 06/30/2026: https://calhfa.ca.gov/homeownership/limits/income/income-cadfa.pdf
- Dream For All: https://calhfa.ca.gov/dream/
- CalHFA refinance rules: https://www.calhfa.ca.gov/homeownership/programs/refi.htm
- CalHFA programs: https://www.calhfa.ca.gov/homebuyer/programs/index.htm
- CalHFA Find a Loan Officer: https://calhfa.ca.gov/homebuyer/lenders.htm
- GSFA Platinum: https://gsfahome.org/programs/dpa/platinum.shtml
- San Bernardino County home ownership resources: https://cdh.sbcounty.gov/home-ownership-resources/
Disclosures
Colleen Olivas, NMLS #379721 | Branch NMLS #2882133 | New American Funding, LLC, NMLS #6606 | Equal Housing Lender. This page is educational and is not a commitment to lend. Programs, terms, guidelines, income limits and availability are subject to change and eligibility requirements. Down payment assistance programs have eligibility rules; funds are limited, subject to availability and not available to everyone. Loans are subject to credit approval and underwriting. Not tax or legal advice. Licensed by the Department of Financial Protection and Innovation under the California Residential Mortgage Lending Act. Loans made or arranged pursuant to a California Financing Law license. For licensing information, visit www.nmlsconsumeraccess.org.