Buyer guide with Colleen Olivas
FHA Loans in the Inland Empire (2026): County Limits and How to Choose an FHA Lender
By Colleen Olivas, NMLS #379721, who started in escrow and worked her way through every role in mortgages, up to underwriter. The Brandon Drew Group, a division of New American Funding Last reviewed November 2026
Quick answer
Look for a HUD-approved lender (HUD is the U.S. Department of Housing and Urban Development) and a licensed loan officer. You can check both for free, on HUD's own site and on NMLS (the Nationwide Multistate Licensing System). No one can honestly name the "best" FHA lender near Rancho Cucamonga, so we won't. For 2026, HUD's FHA loan limit for a one-unit home in San Bernardino County and Riverside County is $690,000. That is the most FHA will insure. It is not a price or an offer. On credit, Mortgagee Letter 2026-11, HUD's official notice to lenders, says 580 and up is eligible for maximum financing. Lenders and programs can ask for a higher score. Subject to eligibility and lender approval.

Key points
- The CFPB (the Consumer Financial Protection Bureau) says the FHA doesn't lend the money directly. Private lenders do. So the lender you pick matters.
- The 2026 FHA limit for a one-unit home in San Bernardino County and Riverside County is $690,000. Two, three and four units have higher limits, shown in the table below.
- Credit has a HUD floor, and lenders can ask for more. Read our credit score guide for the full picture.
- You can check a lender and a loan officer yourself, for free.
- If you want a condo, check early that the project is FHA-approved.
- FHA can be paired with down payment help from CalHFA or GSFA. Programs have eligibility rules, and funds are limited and subject to availability.
On this page (7 sections)
Opening
Every lender says it is the right choice, so this guide gives you facts you can check yourself on government websites.
2026 FHA limits in San Bernardino and Riverside Counties
A loan limit is the most FHA will insure on a home in a given county. It is not the price of a home. It is not what you will be offered. What you can borrow depends on your finances and the lender's approval.
San Bernardino County and Riverside County are in the same area, the Riverside-San Bernardino-Ontario metro area (Ontario, California). That is why they share limits. These are the 2026 forward mortgage limits as of January 1, 2026, from HUD's FHA Mortgage Limits lookup.
| Home type | 2026 FHA limit, San Bernardino and Riverside Counties |
|---|---|
| One unit | $690,000 |
| Two units | $883,300 |
| Three units | $1,067,750 |
| Four units | $1,326,950 |
Limits differ by county. You can look up any county in the same tool.
HUD also sets a range for every county. HUD's news release No. 25-145 of December 11, 2025 set the 2026 one-unit low-cost area floor at $541,287 and the high-cost area ceiling at $1,249,125. These limits apply to case numbers assigned on or after January 1, 2026. A case number is the number HUD assigns to an FHA loan.
HUD announced the 2026 limits on December 11, 2025; check HUD's lookup for the current year.
Credit scores: HUD's floor vs. what lenders ask
HUD sets the lowest credit scores FHA will insure. Mortgagee Letter 2026-11, dated October 8, 2026, puts it this way:
- 580 and above: eligible for maximum financing.
- 500 to 579: eligible, but with limited financing (less than the maximum).
- Below 500: not eligible for FHA-insured financing.
The existing score thresholds are unchanged. The letter adds new credit score models for case numbers assigned on or after January 1, 2027. If you plan to buy in 2027, ask your lender which model they will use.
HUD's number is a floor, not a promise. A lender may ask for a higher score than HUD does. Down payment help programs may ask for more too. For example, CalHFA's published matrices start at 640. We explain why in our credit score guide.
Credit is one piece. Lenders also look at your income, your debts and your savings. See debt-to-income ratio and what underwriters look for.
How to check an FHA lender and loan officer
Private lenders make FHA loans, not the FHA itself. That means the lender you pick matters. Here are three checks that take about ten minutes.
1. Is the lender on HUD's list? HUD has a single family lender list search. Look up the company name there.
2. Is the loan officer licensed? Every loan officer has an NMLS number. NMLS Consumer Access lets you search by name or number and see their license information. The number should also be on their website, emails and ads. If it is not, ask why.
3. Will they put things in writing? Ask for the numbers on paper, not just by phone. Ask what is required before you can get approved. Ask who your contact will be from start to finish, and whether your file will change hands.
If you want to compare more than one lender, do. A good lender will not mind.
When you are looking at CalHFA programs, also read how to choose a CalHFA-approved lender. CalHFA's approved lender list shows New American Funding, LLC at 8463 Haven Avenue, #B, Rancho Cucamonga as a CalHFA-approved lender branch. That is our branch. Check it yourself rather than taking our word for it.
Condos: check FHA approval early
If you are looking at a condo, the project itself matters, not only you. HUD's FHA-approved condominium search "allows users to search for FHA-approved condominium projects by location, name, or status".
Check this early. Do it before you fall in love with a unit, and before you write an offer. If the project is not approved, FHA may not be an option for that home. It is much easier to learn that on day one than on day twenty.
FHA with down payment help: CalHFA and GSFA
Two programs often come up in the Inland Empire.
CalHFA FHA. According to CalHFA's programs page, "The CalHFA FHA Program is an FHA-insured loan". It can be paired with CalHFA MyHome Assistance. CalHFA's MyHome program is "only available through a CalHFA-approved lender." CalHFA's 2026 income limit for San Bernardino and Riverside Counties is $210,000. Our Inland Empire income limits guide shows how limits work.
GSFA Platinum. The Golden State Finance Authority runs GSFA Platinum, and it can pair with FHA. GSFA sets no GSFA income limit for FHA loans. Your lender may still have its own rules. Read our GSFA Platinum guide to see how it works and what to compare.
These programs have eligibility rules. Funds are limited and subject to availability. They are not available to everyone, and they can change without notice. Check the agency page for current terms.
Mortgage insurance, in plain words
FHA loans come with mortgage insurance. The CFPB says, "Mortgage insurance is required for all FHA loans."
We leave out the numbers here on purpose. Premiums can change, and they depend on the loan. Instead of a number from a web page, ask your lender to show you the cost for your loan in writing. Ask what you pay at closing, what you pay each month, and how long you pay it. Then put two lenders' answers side by side.
Your next step
Talk it through with Colleen
A short call helps you know what to ask and what to have ready. No pressure.
 Free guide · PDF · California editionThe Homebuyer's Guide
Pre-approval, CalHFA, GSFA and the other down payment programs, in plain words. Read it at your own pace.
Download the free guide
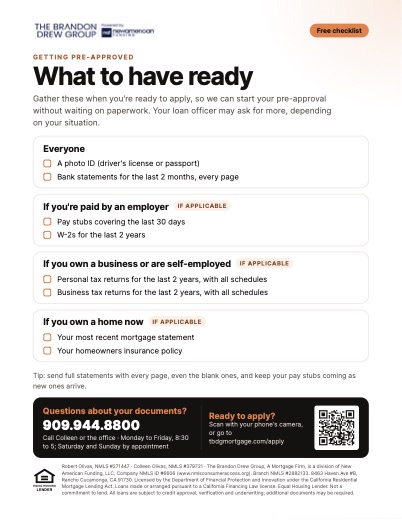 Free checklist · PDF · one pageWhat to have ready
The documents to gather when you're ready to apply, so we can start your pre-approval without waiting on paperwork.
Download the checklist
Questions buyers ask
How do I choose an FHA lender near Rancho Cucamonga?
Check the lender on HUD's lender list, check the loan officer's license on NMLS Consumer Access, and ask for answers in writing. We can't name a "best" lender. That depends on your credit, income, the home and the service you want. Compare at least two. We are happy to be one of them.
What is the FHA loan limit in San Bernardino County in 2026?
As of January 1, 2026, HUD's FHA Mortgage Limits lookup shows $690,000 for one unit, $883,300 for two units, $1,067,750 for three units and $1,326,950 for four units. Riverside County has the same limits because both are in the Riverside-San Bernardino-Ontario metro area. A limit is the most FHA will insure. It is not a price or an offer.
Can I get FHA with a 580 score?
Mortgagee Letter 2026-11 says 580 and above is eligible for maximum financing. A score of 500 to 579 is eligible, but with limited financing (less than the maximum). Below 500 is not eligible. But HUD's number is a floor. Your lender, and any down payment program, may ask for a higher score. Approval also depends on income, debts and the home. Subject to eligibility and lender approval.
→ Read: Credit score minimums in 2026
Can I use FHA with a condo?
Check first whether the condo project is FHA-approved; if it isn't, FHA may not be an option for that home. HUD's condo search lets you look by location, name or status. Check before you make an offer.
Can FHA be paired with down payment help?
It can be paired with some programs. CalHFA FHA can be paired with MyHome Assistance, and GSFA Platinum can pair with FHA. Each program has its own rules, and funds are limited and subject to availability. Ask a CalHFA-approved lender about the current terms.
→ Read: Credit score minimums in 2026
Sources12 sources · show all
Every official site we use is also on one page: Official sources we use and trust.
Check each page directly. Limits and rules change. All items below were checked November 2, 2026.
- HUD, FHA Mortgage Limits lookup: https://entp.hud.gov/idapp/html/hicostlook.cfm
- HUD news release No. 25-145, December 11, 2025: https://www.hud.gov/news/hud-no-25-145
- HUD Mortgagee Letter 2026-11, October 8, 2026: https://www.hud.gov/sites/default/files/hudclips/documents/2026-11hsgml.pdf
- CFPB, FHA loans (last modified June 30, 2025): https://www.consumerfinance.gov/owning-a-home/fha-loans/
- HUD, single family lender list search: https://www.hud.gov/hud-partners/single-family-lender-list
- NMLS Consumer Access: https://www.nmlsconsumeraccess.org
- HUD, FHA-approved condominium search: https://entp.hud.gov/idapp/html/condlook.cfm
- CalHFA, programs: https://www.calhfa.ca.gov/homebuyer/programs/index.htm
- CalHFA, government loan matrix: https://www.calhfa.ca.gov/homeownership/materials/files/tool-matrix-gov.pdf
- CalHFA, income limits: https://cloud.calhfa.ca.gov/homeownership/limits/income/income.pdf
- CalHFA, approved lender list: https://www.calhfa.ca.gov/apps/approvedlenders/
- GSFA, income limits: https://gsfahome.org/programs/dpa/limits.aspx
Disclosures
Colleen Olivas, NMLS #379721. Robert Olivas, NMLS #271447. The Brandon Drew Group, a division of New American Funding, LLC, Company NMLS ID #6606 (www.nmlsconsumeraccess.org). Branch NMLS #2882133. 8463 Haven Avenue, Suite B, Rancho Cucamonga, CA 91730.
Equal Housing Lender.
Licensed by the Department of Financial Protection and Innovation under the California Residential Mortgage Lending Act. Loans made or arranged pursuant to a California Financing Law license.
FHA loan limits are the most FHA will insure. They are not prices or offers. Down payment assistance programs have eligibility rules, funds are limited and subject to availability, and they are not available to everyone. Program terms, income limits and loan limits can change without notice. This is for information only. It is not a commitment to lend or a rate quote. Loans are subject to eligibility, credit approval and underwriting. Not tax or legal advice. For licensing information, visit www.nmlsconsumeraccess.org.