Buyer guide with Colleen Olivas
VA Home Loans in California (2026): How They Work, the Funding Fee, and What's Different Here
By Colleen Olivas, NMLS #379721, who started in escrow and worked her way through every role in mortgages, up to underwriter. The Brandon Drew Group, a division of New American Funding Last reviewed November 2026
Quick answer
A VA-backed home loan is a mortgage from a private lender, guaranteed by the U.S. Department of Veterans Affairs. VA says that in most cases its guaranty "allows you to buy a home with no down payment," and VA loans don't require monthly mortgage insurance. Most buyers pay a one-time VA funding fee unless they're exempt. You need a Certificate of Eligibility, and you still have to qualify with a lender and live in the home. Subject to eligibility and lender approval.

Key points
- For a VA-backed loan, VA guarantees the loan and a private lender makes it. We are not part of VA.
- VA says there's no down payment needed in most cases, but you'll still have closing costs.
- VA loans don't require monthly mortgage insurance. Instead there's a one-time funding fee, and VA lists who's exempt.
- You need a Certificate of Eligibility (COE). You can request it online, or a lender can request it for you.
- You can use the benefit again after you sell or refinance a home you bought with a VA loan.
- In California, ask about property taxes and Mello-Roos, CalHFA's VA loan, and CalVet, a separate state program.
On this page (8 sections)
How a VA loan works
VA explains that its loan guaranty "protects your lender from losing money if you default on your loan," and that "In most cases, this guaranty allows you to buy a home with no down payment." For a VA-backed loan, a private lender makes the loan and sets the rate. VA notes that "Lenders offer competitive interest rates on VA-backed purchase loans," so compare more than one lender.
Even with full entitlement, VA says "your lender will still need to approve you for a loan." VA itself doesn't set a minimum credit score: "We don't require a minimum credit score, but some lenders do have a requirement, so be sure to contact more than one lender to compare."
Who's eligible, and the Certificate of Eligibility
VA's eligibility page lists service requirements by service period, and some surviving spouses may qualify. For someone serving now: "If you've served for at least 90 continuous days (all at once, without a break in service), you meet the minimum active-duty service requirement." Veterans' requirements depend on when they served, so check VA's table for yours.
VA describes the Certificate of Eligibility (COE) as the document that shows your entitlement. VA says: "You can request a COE online right now, or you can ask your lender to submit an online application for you." You can ask us to request it when you apply.
VA adds: "To get financing for a VA-backed home loan, you must meet credit, income, and occupancy requirements from both us and your lender." For a purchase loan, VA says, "You will live in the home you're buying with the loan."
How much you can borrow
How much you can borrow depends on your entitlement, the lender's approval and the appraisal:
- The appraisal sets a cap. VA says "The maximum VA loan on an individual property is either the appraised value of the property or the purchase price, whichever is lower."
- If you don't have full entitlement, VA says "your remaining bonus entitlement is based on the county loan limit where you plan to buy or refinance a home, minus the amount of your entitlement you've already used." VA's page shows how to find your county's limit.
- The math has a few steps. We'll walk through your own COE with you rather than guess.
The VA funding fee
VA explains that "The VA funding fee is a one-time payment that the Veteran, service member, or survivor pays on a VA-backed or VA direct home loan," and that it "helps to lower the cost of the loan for U.S. taxpayers since the VA home loan program doesn't require down payments or monthly mortgage insurance."
VA says it bases the fee on "The type of loan you get" and "The total amount of your loan," among other factors. VA's page has the current chart. You can include the fee in your loan or pay it at closing.
You won't pay the funding fee if any of these are true (VA's list):
- You're receiving VA compensation for a service-connected disability.
- You're eligible to receive that compensation but you're receiving retirement or active-duty pay instead.
- You're receiving Dependency and Indemnity Compensation (D.I.C.) as the surviving spouse of a Veteran.
- You're a service member who received a proposed or memorandum rating before the loan closing date that says you're eligible for compensation because of a pre-discharge claim.
- You're an active-duty member of the Armed Forces and, on or before closing, you provide evidence that you received a Purple Heart.
Closing costs and seller credits
No down payment doesn't mean no cash at closing. There are closing costs, and the funding fee unless you're exempt. VA says "You (the buyer) and the seller can negotiate who will pay closing costs." It also says: "We allow home sellers or builders to offer credits to cover some or all of the buyer's closing costs. We don't limit credits for a loan's closing costs, but we do limit seller's concessions to no more than 4% of your home's reasonable value." Ask us which seller credits count toward VA's limit.
Using your VA benefit again
VA says you can "Use your VA loan benefit again if you sell or refinance a home you bought with a VA-backed home loan." If you still own a home with a VA loan, you may have remaining entitlement for another purchase. That's the remaining-entitlement math above. Read how one family did it in Keys down the street from their first grandchild.
What's different in California
- Property taxes and Mello-Roos. San Bernardino County's Assessor explains that under Proposition 13 the property tax "cannot exceed 1% of the property's assessed value, plus any bonds or fees approved by the voters." Your county assessor can confirm yours. Some homes sit in a Community Facilities District with a Mello-Roos special tax. It depends on the address, not the city, so ask for the seller's Notice of Special Tax early. Our Mello-Roos guide shows how to read one.
- CalHFA's VA loan. CalHFA describes its VA program as "a VA-insured loan featuring a CalHFA fixed interest rate first mortgage." Ask us how it compares with a standard VA loan for you. See CalHFA first-time buyer loans.
- CalVet Home Loans. This is a separate program. CalVet says it is "a California state agency authorized to provide home loans to California veterans and their families," and that it "works exclusively with Veterans purchasing a primary home in California." It's worth comparing with a VA-guaranteed loan.
How to start
- Request your COE, or ask us to request it for you.
- Check whether you're exempt from the funding fee using VA's list above.
- Get pre-approved and compare more than one lender, as VA suggests.
- Ask about the property. Mello-Roos, HOA dues and the appraisal all matter for a VA purchase.
- Ask for a Loan Estimate so you can see your closing costs and the funding fee before you commit.
The bottom line
A VA loan is a benefit you earned through your service, and it's worth understanding before you shop for a home. VA guarantees it, a lender makes it, and in most cases you can buy with no down payment and no monthly mortgage insurance. Bring your COE, or ask us to request it when you apply, and we'll walk through your entitlement, the funding fee and your California costs with you.
Your next step
Talk it through with Colleen
A short call helps you know what to ask and what to have ready. No pressure.
 Free guide · PDF · California editionThe Homebuyer's Guide
Pre-approval, CalHFA, GSFA and the other down payment programs, in plain words. Read it at your own pace.
Download the free guide
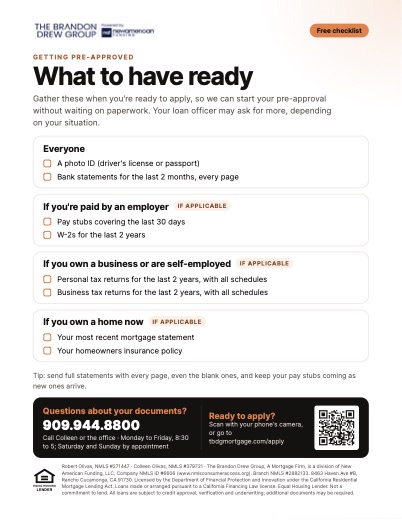 Free checklist · PDF · one pageWhat to have ready
The documents to gather when you're ready to apply, so we can start your pre-approval without waiting on paperwork.
Download the checklist
Questions buyers ask
Can I buy a home with no money down with a VA loan?
VA says that in most cases its guaranty "allows you to buy a home with no down payment," as long as the sales price isn't higher than the appraised value. You'll still have closing costs, and the funding fee unless you're exempt. Sellers can offer credits toward closing costs, within VA's rules.
Does a VA loan have mortgage insurance?
No monthly mortgage insurance. VA charges a one-time funding fee instead, and VA lists who's exempt, including Veterans receiving compensation for a service-connected disability.
How do I get my Certificate of Eligibility?
VA says you can request it online, or ask your lender to submit an online application for you. You can ask us to request it when you apply.
→ Read: How we work
Can I use my VA loan more than once?
Yes. VA says you can use the benefit again if you sell or refinance a home you bought with a VA loan. If you don't have full entitlement, VA says your remaining entitlement is based on your county's loan limit, minus what you've already used.
Is there a minimum credit score for a VA loan?
VA says it doesn't require one, but "some lenders do have a requirement, so be sure to contact more than one lender to compare."
→ Read: Credit score minimums
What's the difference between a VA loan and CalVet?
A VA-backed loan is made by a private lender and guaranteed by VA. CalVet Home Loans is a California state agency authorized to provide home loans to California veterans and their families, funded by voter-approved state bonds. They're separate programs, so compare both.
→ Read: CalHFA first-time buyer loans
Sources8 sources · show all
Every official site we use is also on one page: Official sources we use and trust.
Sources re-checked November 8, 2026.
Check each page directly. Rules and limits change. All items below were read November 7, 2026.
- VA, VA home loan entitlement and limits (last updated August 12, 2025): https://www.va.gov/housing-assistance/home-loans/loan-limits/
- VA, Purchase loan (last updated January 7, 2026): https://www.va.gov/housing-assistance/home-loans/loan-types/purchase-loan/
- VA, Eligibility for VA home loan programs (last updated September 22, 2026): https://www.va.gov/housing-assistance/home-loans/eligibility/
- VA, VA funding fee and loan closing costs (last updated October 5, 2026): https://www.va.gov/housing-assistance/home-loans/funding-fee-and-closing-costs/
- CalHFA, homebuyer loan programs: https://www.calhfa.ca.gov/homebuyer/programs/index.htm
- CalVet Home Loans, Why CalVet?: https://www.calvet.ca.gov/HomeLoans/Pages/Why-CalVet.aspx
- San Bernardino County Assessor, Proposition 13: https://arc.sbcounty.gov/what-is-proposition-13/
- NMLS Consumer Access: https://www.nmlsconsumeraccess.org
Disclosures
Colleen Olivas, NMLS #379721. Robert Olivas, NMLS #271447. The Brandon Drew Group, a division of New American Funding, LLC, Company NMLS ID #6606 (www.nmlsconsumeraccess.org). Branch NMLS #2882133. 8463 Haven Avenue, Suite B, Rancho Cucamonga, CA 91730.
Equal Housing Lender.
Licensed by the Department of Financial Protection and Innovation under the California Residential Mortgage Lending Act. Loans made or arranged pursuant to a California Financing Law license.
This is for information only. It is not a commitment to lend or a rate quote. VA-backed loans are guaranteed by the U.S. Department of Veterans Affairs. We are not part of VA, CalHFA or CalVet, and this page was not written or approved by any of them. VA eligibility, entitlement, funding fee rules and loan limits can change. This page covers VA loans only; for USDA rural home loans, see the U.S. Department of Agriculture. Loans are subject to credit approval and underwriting. For licensing information, visit www.nmlsconsumeraccess.org.